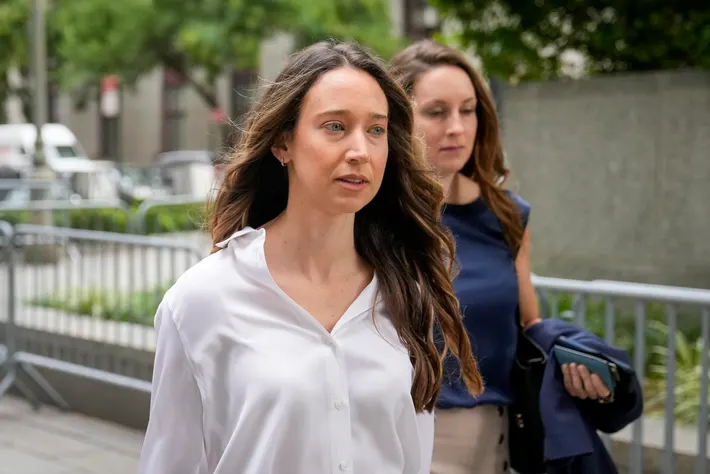
Charlie Javice, the founder of student-aid startup Frank, has been found guilty of fraud in a high-profile case involving JPMorgan Chase. The court ruled that Javice misled the banking giant into acquiring her company for $175 million by fabricating user data to inflate the startup’s value. Prosecutors detailed how Javice and her associates created fake customer accounts to deceive JPMorgan into believing that Frank had over 4 million real users, while in reality, the actual number was significantly lower.
Javice’s legal team attempted to argue that she was a victim of aggressive acquisition tactics by JPMorgan, but the evidence presented, including emails and financial records, painted a different picture. Investigators revealed that Javice paid a data scientist to generate fake user information, making Frank appear far more successful than it actually was. Once the acquisition was complete, JPMorgan quickly uncovered inconsistencies in the customer database, leading to an internal investigation and a subsequent lawsuit.
The verdict has sent shockwaves through the tech and financial sectors, highlighting the growing scrutiny around startup valuations and due diligence in acquisitions. Legal experts believe this case could set a precedent for how courts handle corporate fraud in the startup world. Industry analysts also speculate that investors and financial institutions will now take extra precautions when evaluating companies for potential investments or buyouts.
Javice now faces significant legal consequences, including possible prison time and financial penalties. The ruling serves as a stark warning to entrepreneurs and investors about the severe repercussions of financial misconduct. As the tech industry continues to evolve, this case underscores the importance of transparency, ethical business practices, and the risks associated with exaggerated valuations.


 HOME
 Foodies
 Drinks
 Fruits & Veggies
 Supermarket
 Beauty & Health
 Electronics
 Fashion
 Live Tv